Housing · Canada
Home Buyers’ Plan (HBP) in Canada: using RRSP withdrawals without wrecking retirement math
The Home Buyers’ Plan lets eligible buyers withdraw from an RRSP to buy or build a qualifying home without the withdrawal showing up as income — if they follow CRA’s rules and later repay. The current withdrawal limit is $60,000 per eligible person (CRA, verified 20 Sep 2026). Couples who each qualify can each use their own limit. That is powerful. It is also how households raid the only retirement account they have and then miss a repayment year.
This page is a down-payment and repayment map. It is not a filing position. For the FHSA calendar that often sits beside HBP, use the FHSA how-to.
Disclosure: Mortgage tools and brokerage or FHSA account offers are offer types. Saving Optimizer may earn a commission if we later add partner links. We do not currently claim issuer, lender, or broker partnerships. This is not tax, legal, or investment advice. Confirm HBP and FHSA rules in CRA My Account and with a licensed advisor.
Key takeaways
- CRA HBP limit: $60,000 per eligible participant (verified 20 Sep 2026). A qualifying couple can each withdraw up to that amount from their own RRSP.
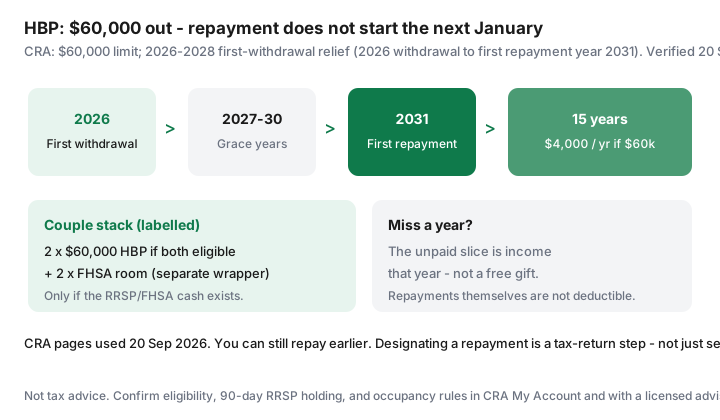
- Repay over 15 years. Temporary relief for a first withdrawal between 1 Jan 2026 and 31 Dec 2028 starts that clock in the fifth year (2026 withdrawal → first repayment year 2031).
- You can often use HBP and an FHSA qualifying withdrawal on the same home if you meet each program’s rules independently.
- 90-day RRSP holding, first-time / occupancy, and Form T1036 are the usual traps — confirm on canada.ca, not a group chat.
- Do not drain the RRSP if repayment would become taxable income you cannot absorb, or if the account is your only retirement engine.
Current withdrawal limit basics ($60,000 per person)
CRA’s Home Buyers’ Plan page: you may withdraw from your RRSPs to buy or build a qualifying home for yourself or for a specified disabled person. The HBP withdrawal limit is $60,000. Amounts above that are income, and the issuer withholds tax on the excess. Multiple withdrawals are allowed only in the calendar year of the first withdrawal and in January of the next year. Form T1036 is the usual request for each withdrawal.
Eligible joint buyers can each use their own $60,000 if each person independently qualifies. That is not “$120,000 from one RRSP.” Locked-in accounts are the usual no. New RRSP contributions generally need to have been in the plan for 90 days before a qualifying withdrawal — last-minute dumps are how people create a mess.
Repayment timeline and 2026–2028 temporary relief overview
Default rule in the Income Tax Act world: the 15-year repayment starts the second year after the first withdrawal. Budget 2024 stretched the grace period for first withdrawals from 1 Jan 2022 to 31 Dec 2025. CRA’s HBP page (and the 2026 Spring Economic Update supplementary information) extend that five-year start for first withdrawals from 1 Jan 2026 through 31 Dec 2028. CRA’s example: first withdrawal in 2026, first repayment year 2031.
You repay by contributing to an RRSP, PRPP, or SPP in the year the repayment is due or in the first 60 days of the next year, then designating the amount as an HBP repayment on the return. A contribution you also try to deduct as a regular RRSP deduction is a sequencing problem for a tax advisor. Miss the designated amount and that slice is income that year. Repayments themselves are not a second deduction — you already had the deduction when the money went in the first time.
You may repay earlier than 2031. Relief is optional breathing room, not a dare to spend the cash twice.
Using HBP and FHSA together for one home
CRA is explicit: you can withdraw under the HBP and make a qualifying FHSA withdrawal for the same qualifying home if you meet all conditions at the time of each withdrawal. They are different wrappers. FHSA contributions are generally deductible and a qualifying withdrawal can be tax-free without a 15-year payback. HBP is a loan from your future self. Stacking is how a couple with years of room and RRSP balances funds a down payment without a taxable RRSP raid. Stacking without a repayment calendar is how the 2031 tax return surprises you.
FTHBI shared-equity applications ended 21 Mar 2024 (CMHC). Do not plan on a new Incentive cheque beside HBP.
Eligibility traps first-timers miss
- First-time / prior-ownership tests (including the usual look-back on occupying a home you owned). “I had a name on title for eight months in 2021” is the classic fail. Confirm CRA’s current participation page.
- A written agreement to buy or build, and the intent to occupy as a principal residence on the CRA timeline (commonly discussed as within one year — read the current page).
- Withdrawing from an RRSP that has not held the contribution for 90 days.
- Re-participating after a previous HBP: possible only if you have repaid and meet the rules again — not “I did this in 2018, whatever.”
- Using HBP for a rental you will not occupy.
How HBP changes your down-payment and mortgage insurance needs
Cash at closing can push you over 20% and off default insurance, or down a published premium tier (5% vs 10% vs 15% down). That can matter more than a 0.10% rate shop. It can also make a thin emergency fund thinner — the RRSP money is not still sitting there for a special assessment. Run the stress-test worksheet on the new loan size. Then run year-one cash so the down payment is not the last dollar you have.
Worked example for a couple stacking accounts
| Wrapper | Person A | Person B |
|---|---|---|
| FHSA qualifying withdrawal | Up to funded room ($8,000 / $40,000 lifetime design) | Same, if they opened and funded |
| HBP RRSP withdrawal | Up to $60,000 | Up to $60,000 |
| Repayment if both take $60,000 and wait | $4,000 / year from 2031 | $4,000 / year from 2031 |
| Combined repayment | $8,000 / year starting 2031 — put it in the mortgage budget now | |
If that $8,000 / year is also the year daycare starts, you did not “get a free down payment.” You scheduled a second housing bill.
When not to drain the RRSP
- The RRSP is the household’s only retirement vehicle and the home is a short-stay (see stay-horizon math).
- You would sell investments at a loss inside the RRSP to raise cash this month.
- Repayment would be a hope, not a line on the 2031 budget — missed years are taxable.
- You already have enough cash to close and keep a reserve; the tax wrapper is doing more harm than good.
- You are close to needing RRSP income. HBP is a first-home tool, not a bridge to retirement income.
Sources & date stamps
- CRA, The Home Buyers’ Plan — $60,000 limit; HBP + FHSA on the same qualifying home; 2026–2028 first-withdrawal repayment-start example (2026 → 2031). Pages used 20 Sep 2026.
- CRA, How to repay amounts withdrawn under the HBP — 15 years; designation mechanics; missed-year income treatment.
- CRA, How to make withdrawals — Form T1036; same-year / following-January window; excess over $60,000 is income.
- Department of Finance, Spring Economic Update 2026 supplementary information — proposes extending the five-year grace period through 2028 first withdrawals.
- CRA FHSA pages — $8,000 first-year room, $40,000 lifetime contributions (verify in My Account).
- CMHC, First-Time Home Buyer Incentive — new applications ended 21 Mar 2024.
Frequently asked questions
What is the Home Buyers’ Plan limit in 2026?
CRA’s published HBP withdrawal limit is $60,000 per eligible person (verified 20 Sep 2026). Eligible joint buyers can each withdraw up to that amount from their own RRSP if they each meet the rules. Amounts above $60,000 are income.
When do I start repaying a 2026 HBP withdrawal?
CRA’s temporary relief for a first withdrawal between 1 January 2026 and 31 December 2028 starts the 15-year repayment in the fifth year. A 2026 first withdrawal has a first repayment year of 2031 in CRA’s example language. You may repay sooner. Confirm on canada.ca before you file.
Can I use HBP and an FHSA on the same home?
Often yes at a high level if you meet each program’s conditions at the time of each withdrawal. CRA says this explicitly. It is still a tax-and-mortgage sequencing problem. This is not a filing position.
Is an HBP repayment deductible?
No. You are putting borrowed-from-yourself RRSP money back. Miss the designated minimum and that slice is included in income. Regular RRSP deductions and HBP designations are easy to mix up — use a licensed tax advisor.
Is this tax advice?
No. It is a down-payment and repayment calendar. Account offers and mortgage tools are affiliate types only. We do not claim brokerage partnerships.