
Weddings · Canada
Wedding Insurance in Canada: Cancellation vs Liability, What Policies Cover and Exclude
Wedding insurance in Canada is usually two separate covers sold together or apart: cancellation cover, which repays non-refundable deposits and contracted costs if the wedding is cancelled or cut short for a reason listed in the policy, and special event liability cover, which pays claims if a guest is hurt or venue property is damaged. Cancellation cover never pays for a change of heart, and the published Canadian policy wording reviewed here excludes cancellations linked to communicable disease that lead to quarantine or travel advisories. Liability cover is the part venues tend to require. Ontario's special occasion permit rules do not themselves require liability insurance, but venues may.
Key takeaways
- Cancellation cover repays lost deposits for listed reasons only.
- Liability cover pays third-party injury or property damage claims.
- Change of heart is excluded; read the communicable disease exclusion.
- Venues, parks and rental companies may require liability insurance.
- Ontario's special occasion permit rules do not require it; your venue might.
- Example with made-up inputs: when cover pays off.
Cancellation cover vs liability cover
| Cancellation cover | Liability cover | |
|---|---|---|
| What it pays | Non-refundable deposits and contracted costs | Claims for bodily injury or property damage to others |
| Triggered by | A listed cause forcing cancellation or curtailment | An accident at the event |
| Who requires it | Nobody; your choice | Often venues, parks or rental companies |
| Size the limit by | Total deposits and contracts at risk | The venue's written requirement |
| Common add-on | Honeymoon cancellation, vendor failure | Host liquor liability |
What one Canadian policy wording covers
Policies differ, so the only reliable guide is the wording of the policy you buy. As an example, the P.A.L. Weddinguard wording (form 01/13-W, updated 1 June 2024, underwritten at Lloyd's) lists these cancellation causes:
- Death, injury, illness, compulsory quarantine, witness summons, jury duty or involuntary unemployment of either of the couple or listed immediate family. Unemployment means the person must qualify for Employment Insurance.
- An unforeseen job posting overseas for either of the couple.
- The ceremony or reception venue being unable to host after damage from any cause, a disease outbreak at the premises, or closure due to insolvency or by the local authority.
- Bridal attire lost or damaged beyond repair within five working days of the wedding.
- The booked wedding transport not showing up.
- Extreme weather on the day that poses a serious safety threat or stops at least half the guests reaching the event, only if the policy was bound at least 15 days before the wedding.
The same wording has further sections, each with its own limit in the declarations: honeymoon cancellation tied to a covered wedding cancellation, lost deposits if a supplier fails financially or booked live entertainers do not appear, retakes if the professional photographer or videographer does not appear, attire, wedding gifts, wedding bands from seven days before the wedding to the end of the reception, cake and flowers, stationery and rented property such as tents, tables and audio equipment. A $100 deductible applies to each loss under each section.
What it excludes
| Exclusion | What it means |
|---|---|
| Disinclination to marry | No payment if either of the couple does not show up because they no longer want to marry |
| Tents and marquees | Cancellation after damage to tents or similar outdoor locations is excluded from cancellation cover |
| Pregnancy or childbirth | Excluded as a cancellation cause |
| Prior terminal diagnosis | Excluded if diagnosed before the application |
| Communicable disease | Excluded where it leads to quarantine, movement restrictions or travel advisories |
| Jewellery and money | Excluded under the property sections, though wedding bands have their own section |
| Hazardous activities | Injury from listed activities, including winter sports other than curling or skating |
Read the property section valuation rule too: in the example wording, property claims pay the actual cash value, not the replacement cost, and gift claims need the original purchase receipt.
When liability insurance is required
- Venues: a venue contract may set a liability amount and ask to be named as an additional insured. Ask for the requirement in writing before you buy.
- Ontario special occasion permits: AGCO and LCBO guidance says provincial rules do not require liability insurance, but the venue may.
- Toronto parks: picnic permits add an insurance charge of $33.48 for 1 to 25 people or $65.88 for 26 to 100 people, and commercial photography in parks needs $2 million in third-party liability insurance naming the City of Toronto as an additional insured.
- Drones: Transport Canada says insurance is not required but is recommended; any drone operator should carry their own.
- Vendors: ask caterers, rental companies and entertainers for their own certificates of insurance.
Does home or tenant insurance cover the wedding?
Some home and tenant policies include personal liability that may extend to events you host, and some do not, especially for events away from your home or with liquor service. Ask your insurer in writing whether your policy covers a wedding at your home or at a rented venue, what the limit is, and whether host liquor liability is included. Do not assume. Backyard weddings in particular raise questions about rented tents, guests' injuries and alcohol.
Contracts first, insurance second
Insurance only covers the losses that your contracts leave you with. Ontario's Consumer Protection Act cooling-off periods do not apply to ordinary wedding vendor contracts, so cancellation terms are set by the contract. Before you price insurance, list each deposit, whether it is refundable, and what you owe at each date. That total is the most cancellation cover could ever repay. Related: vendor contracts and deposits.
How to buy
- Get your venue's insurance requirement in writing: limit, additional insured wording, dates.
- Add up deposits and contract amounts that are non-refundable.
- Get the full policy wording, not just a summary, and read the exclusions.
- Check the communicable disease, weather and pre-existing condition terms.
- Buy early: some covers, such as extreme weather in the example wording, only apply if bought well before the date.
- Send the certificate to the venue and keep receipts for everything.
Example with made-up inputs
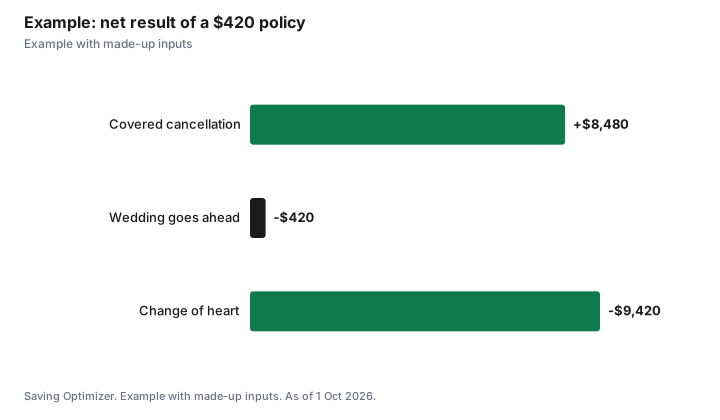
These numbers are an example with made-up inputs. A couple has $18,000 in contracts, of which $9,000 in deposits is non-refundable today. A made-up policy with $15,000 of cancellation cover and $2 million liability costs $420. Scenario 1: the wedding happens; the $420 bought peace of mind and met the venue's liability requirement. Scenario 2: a parent is hospitalized two weeks before and the wedding is cancelled; the couple claims $9,000 in lost deposits, less the $100 deductible, and receives $8,900. Scenario 3: the couple calls it off; nothing is paid.
| Scenario | Paid by insurer | Net to the couple |
|---|---|---|
| Wedding goes ahead | $0 | -$420 |
| Covered cancellation | $8,900 | +$8,480 |
| Change of heart | $0 | -$9,420 |
Common mistakes
- Buying cancellation cover when the venue needs liability cover.
- Assuming disease-related cancellations are covered.
- Buying too late for weather or other time-limited cover.
- Not naming the venue as an additional insured when required.
- Forgetting receipts for gifts and property.
Related: 2027 wedding budget and buying your own wedding alcohol.
Sources
- P.A.L. Insurance Brokers Canada, Weddinguard Wording, form 01/13-W, updated 1 Jun 2024, as of 1 Oct 2026.
- AGCO and LCBO, helloLCBO special occasion permit FAQs, as of 1 Oct 2026.
- City of Toronto, Wedding Ceremonies and Commercial Photography in Parks; Picnic and park permits, toronto.ca, as of 1 Oct 2026.
- Transport Canada, Drone safety: insurance and rules for basic operations, as of 1 Oct 2026.
- Government of Ontario, Your rights under the Consumer Protection Act, ontario.ca, as of 1 Oct 2026.
- Contract and premium amounts in the example are made-up inputs.
Frequently asked questions
What is the difference between wedding cancellation and liability insurance?
Cancellation cover repays non-refundable deposits if the wedding is cancelled for a listed reason. Liability cover pays claims if someone is hurt or property is damaged at the event.
Does wedding insurance cover cold feet?
No. The example Canadian policy wording excludes non-appearance due to disinclination to marry.
Is wedding insurance required in Ontario?
Not by law for a typical wedding, and Ontario's special occasion permit rules do not require liability insurance, but venues may.
Does wedding insurance cover cancellation due to illness outbreaks?
The example wording excludes losses linked to communicable disease that lead to quarantine, movement restrictions or travel advisories. Check your policy.
Does wedding insurance cover bad weather?
The example wording covers extreme weather on the day that poses a serious safety threat or stops at least half the guests attending, only if bought at least 15 days before.
Is there a deductible?
The example wording has a $100 deductible per loss under each section.
Researched and drafted with AI assistance and fact-checked against official Canadian sources. How we create content.
Disclosure: Saving Optimizer may earn a commission if a partner link is added later. No partnership is claimed on this page. Education only, not insurance advice.